Case study · Multifamily value-add · Phoenix
Rise at the Northern
A 108-unit workforce multifamily asset acquired by Rise48 Equity for $21.7M, off-market, through a preemptive full-price bid. Model underwrites to Rise48’s publicly stated operating profile.
Rise48 Equity's acquisition of this 108-unit property for $21.7M is publicly reported — the transaction itself was off-market, closed through a preemptive full-price bid. Operating assumptions, financing terms, renovation scope, and projected returns in this case study are my independent underwriting — not disclosed by Rise48 and not verified against actual deal terms.
Download Excel ModelView the complete assumptions, cash flows, and projected returns.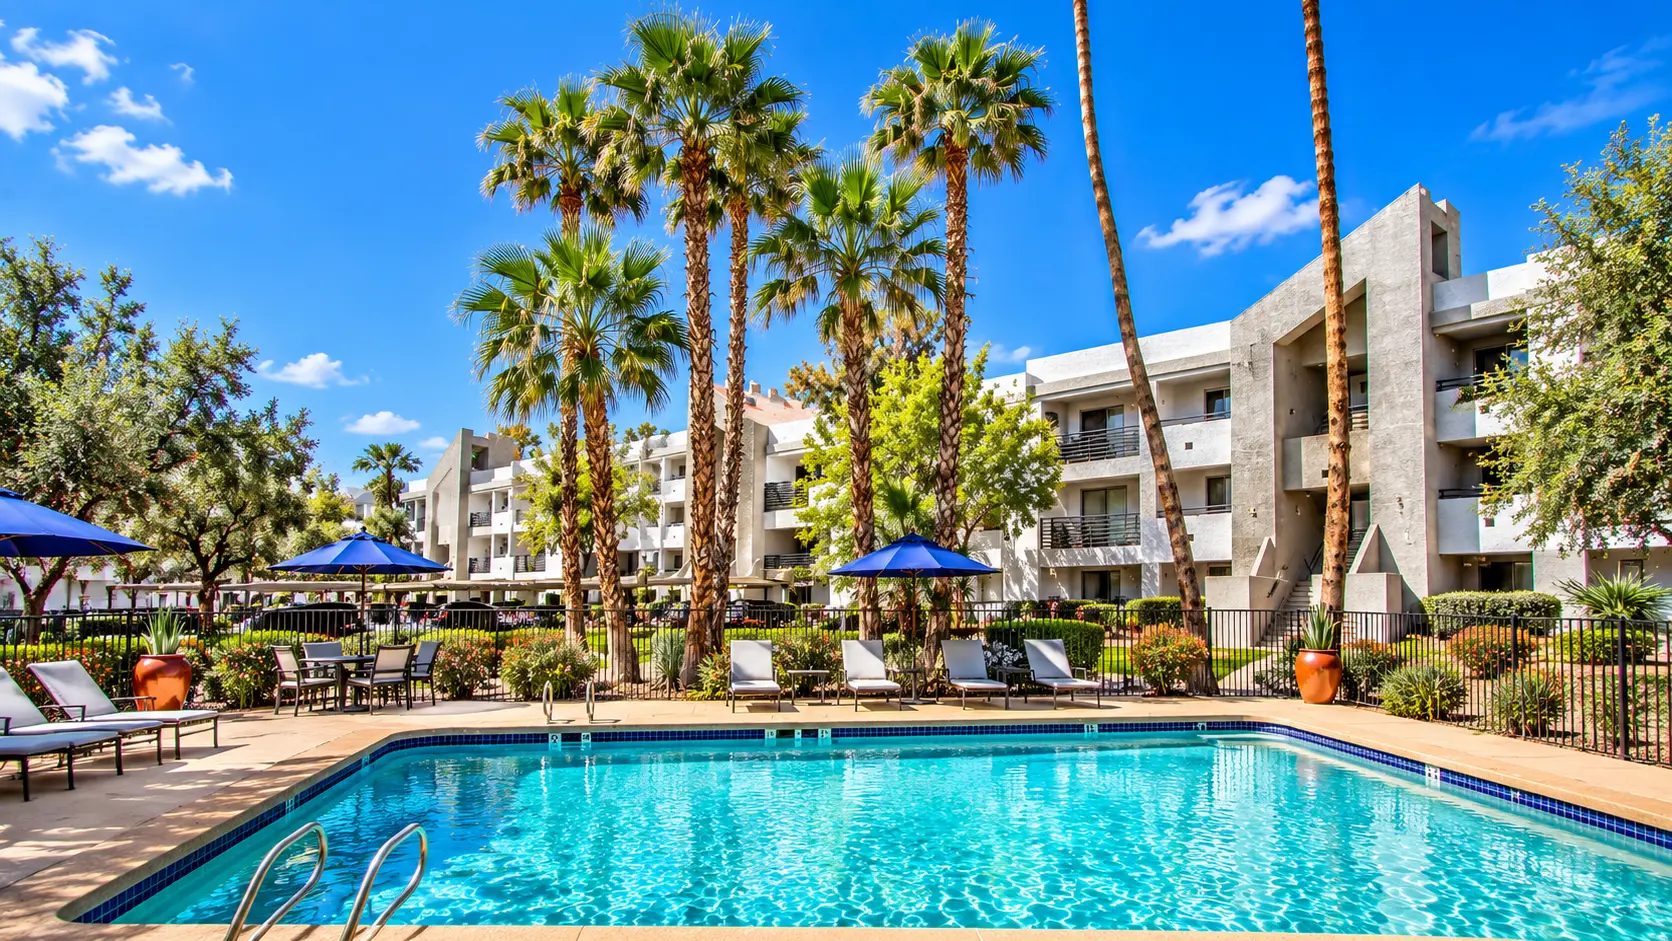
- Levered IRR
- 11.5%
- 5-year hold
- Equity Multiple
- 1.70×
- on $8.8M committed
- Y5 NOI
- $1.40M
- 25% growth over hold
- Exit Value
- $28.0M
- at 5.00% exit cap
01 · The Property
Off-market sourcing in a growing Sun Belt market, financed by agency debt.
The subject is a 1983-vintage, three-story garden-style community of 108 units at 92% occupancy in North Phoenix’s Deer Valley submarket, modeled as an off-market acquisition with a nonrefundable deposit before a formal market process.
The business plan is deliberately light: bulk cable service, valet trash, carport infrastructure, and operational tightening targeting an $89 per-unit monthly rent premium at stabilization. No gut rehab, no heavy construction risk. Capitalized through a 10-year Fannie DUS loan at 65% LTV, fixed at 6.00%, with 5 years of interest-only coverage.
02 · Investment Thesis
A simple, executable plan to drive NOI growth — no financial engineering required.
Sourcing
Off-market acquisition at a basis below replacement cost in a growing Sun Belt market.
Operations
Implement $89 rent premium through light operational upgrades and tight management.
Capital
Agency debt at 6.00% with 5 years of interest-only provides positive leverage and return upside.
03 · Financial Analysis
NOI grows $280K over the hold.
Operations stabilize in Year 2 as the $89 premium phases in across the 108-unit rent roll. By Year 5, NOI grows from $1.12M to $1.40M — a 25% increase.
- Levered IRR
- 11.5%
- Equity Multiple
- 1.70×
- Unlevered IRR
- 8.4%
- Unlevered MOIC
- 1.45×
- DSCR · Y1 → Y5
- 1.32× → 1.65×
04 · Key Assumptions
Underwriting Summary
- Purchase Price
- $21,700,000
- Occupancy
- 92%
- Units / Vintage
- 108 / 1983
- Submarket
- N. Phoenix / Deer Valley
- Price / Unit
- $200,926
- Going-In Cap
- 5.00%
- Senior Debt
- $14.1M · Fannie DUS
- LTV / Term
- 65% / 10-yr · 5-yr IO
- Common Equity
- $8,801,125
- Hold Period
- 5 Years
05 · Analyst Takeaway
Key Takeaways
This deal illustrates the discipline of the Phoenix workforce multifamily playbook — a light operational business plan, agency financing, and positive leverage producing institutional returns without reliance on cap rate compression. The underwrite doesn't rely on cap rate compression — entry and exit caps are modeled flat at 5.00%. All value creation comes from NOI growth driven by the $3,500/unit renovation program, the $89/month rent premium, and market rent inflation. The 5-year interest-only loan structure means ending debt equals starting debt — the thesis works entirely on operating improvements, not financial engineering or market timing. The returns bridge confirms it: NOI growth contributes 100% of positive value creation ($6.30M), cap rate change and debt paydown each contribute 0%, and transaction costs are a $560K drag.