Case study · Multifamily value-add · Issaquah, WA
Vista Ridge Apartments
Independent underwriting of a 91-unit, 1994-vintage garden-style community in Issaquah, Washington, modeling a $37.0M acquisition, a 55-unit renovation program, and agency financing over a five-year hold.
Independent student underwriting. All figures are illustrative model estimates; see the workbook for full assumptions and schedules.
Download Excel ModelView the complete assumptions, cash flows, and projected returns.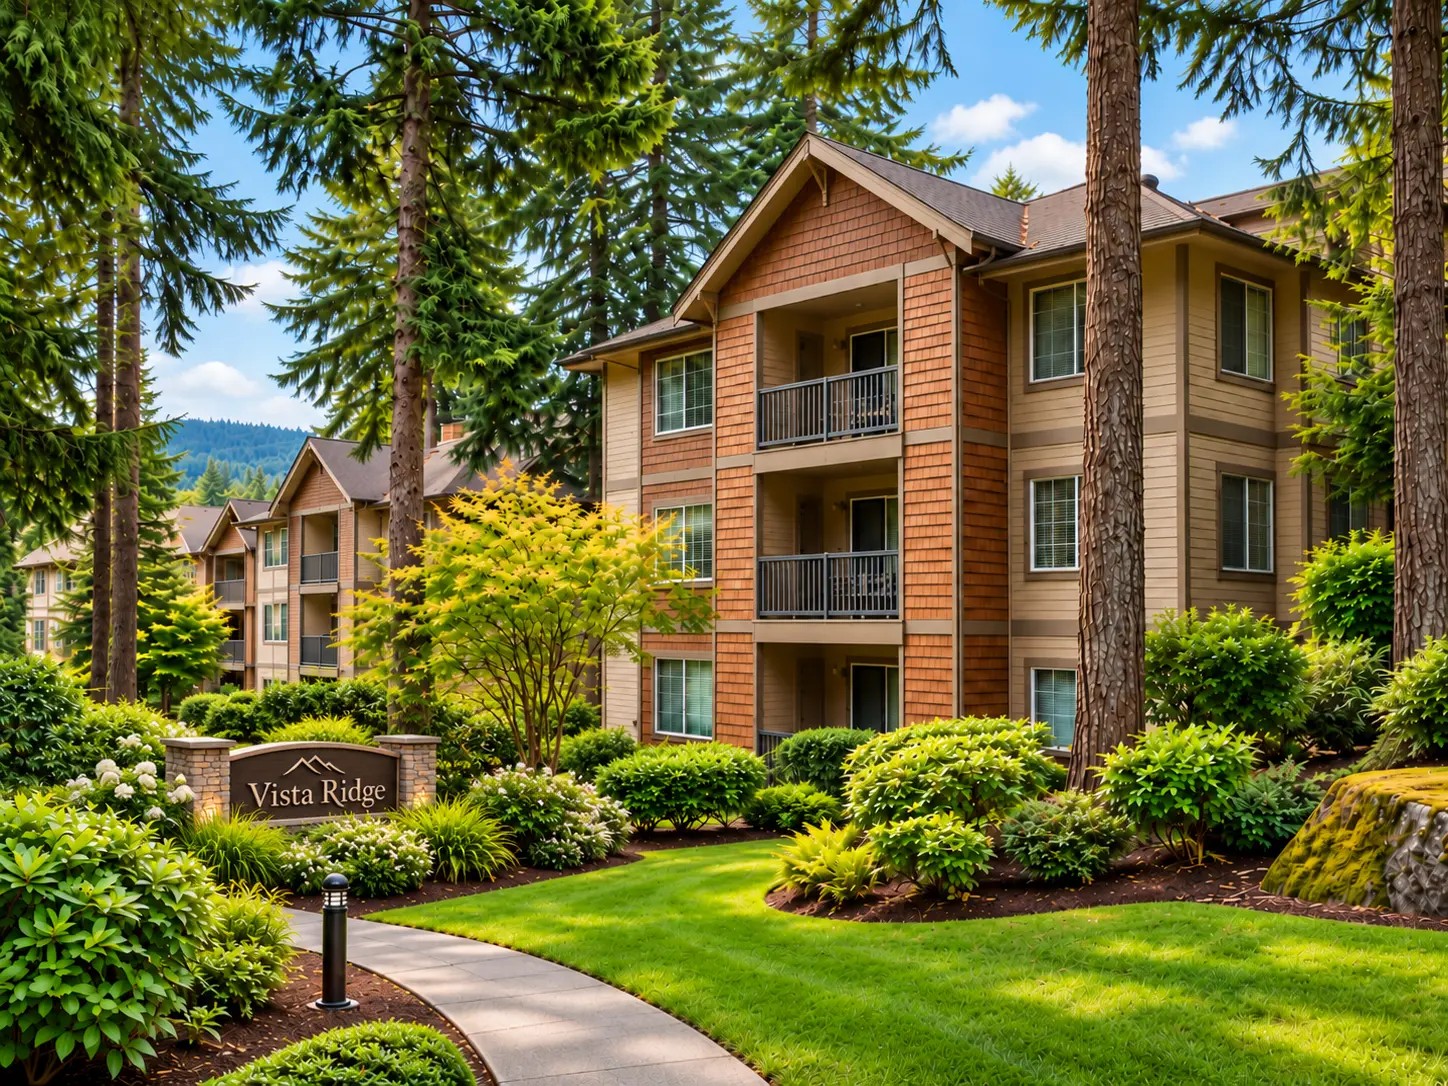
- Levered IRR
- 17.0%
- 5-year hold
- Equity Multiple
- 2.07×
- on $17.5M equity
- Y5 NOI
- $2.74M
- 27% growth over hold
- Exit Value
- $53.3M
- at 5.15% exit cap
01 · The Property
A value-add renovation play in a supply-constrained Seattle suburb.
The subject is a 1994-vintage garden-style community of 91 units at 94% occupancy in Issaquah, Washington, modeled as a $37.0M acquisition at $406,593 per unit and a 6.14% going-in cap rate. In-place rents average $3,104 per month across two- and three-bedroom floor plans.
The business plan is a 55-unit interior renovation program ($20,000 per unit = $1.1M interior capex) plus $650K of common area improvements, totaling $1.75M in value-add capex. The $275/month rent premium per renovated unit generates $181,500 of stabilized annual rent uplift once the renovation program is fully absorbed by Year 4. The remaining 36 units were refreshed by prior ownership and are not re-renovated. Financing is a $22.2M agency loan at 60% LTV, fixed at 5.85% for five years with two years of interest-only.
02 · Investment Thesis
Renovation-led rent growth with conservative agency leverage.
Renovation
Renovate 55 of 91 units over two years at $20,000 per unit, capturing a $275 monthly premium and $181,500 of stabilized annual rent uplift at full capture by Year 4.
Operations
In-place trailing NOI is approximately $2.16M. Year 1 pro-forma NOI steps up modestly to $2.27M as the first 30 units begin renovation and initial premium capture ramps. By Year 5 stabilized, NOI reaches $2.74M — a 27% increase from in-place trailing and 21% from Y1 pro-forma.
Capital
60% LTV fixed-rate agency debt at 5.85% with two years of interest-only keeps DSCR above 1.6× throughout the hold.
03 · Financial Analysis
NOI grows $585K over the hold.
Renovation premiums phase in during Years 1 and 2 while market rent growth compounds. NOI rises from $2.27M in Year 1 to $2.74M in Year 5 — a 21% increase from Y1 pro-forma and 27% from in-place trailing — supporting a $53.3M exit at a 5.15% cap rate. The thesis targets 60% of units for renovation (55 of 91) rather than 100%, since the remaining 36 units received prior ownership refresh. This disciplined scope keeps capex to $1.75M total while capturing most of the achievable rent lift.
- Levered IRR
- 17.0%
- Levered MOIC
- 2.07×
- Unlevered IRR
- 11.4%
- Unlevered MOIC
- 1.64×
- Avg Cash-on-Cash
- 5.9%
04 · Key Assumptions
Underwriting Summary
- Purchase Price
- $37,000,000
- Price / Unit
- $406,593
- Units / Vintage
- 91 / 1994
- Submarket
- Issaquah / Eastside Seattle
- Occupancy
- 94%
- Going-In Cap
- 6.14%
- Senior Debt
- $22.2M · Agency
- LTV / Term
- 60% / 5-yr · 2-yr IO
- Total Equity
- $17,540,000
- Hold Period
- 5 Years
05 · Analyst Takeaway
Key Takeaways
The return case rests on renovation execution and rent growth rather than cap-rate compression — the model exits at 5.15%, roughly 100 basis points inside the 6.14% going-in cap, with value creation split between NOI growth and modest leverage at 60% LTV. The modeled 17.0% levered IRR and 2.07× equity multiple sit within the model's target range, and debt coverage stays comfortable even after amortization begins in Year 3. The key underwriting risk is whether the $275 renovation premium holds in a competitive Eastside rental market.